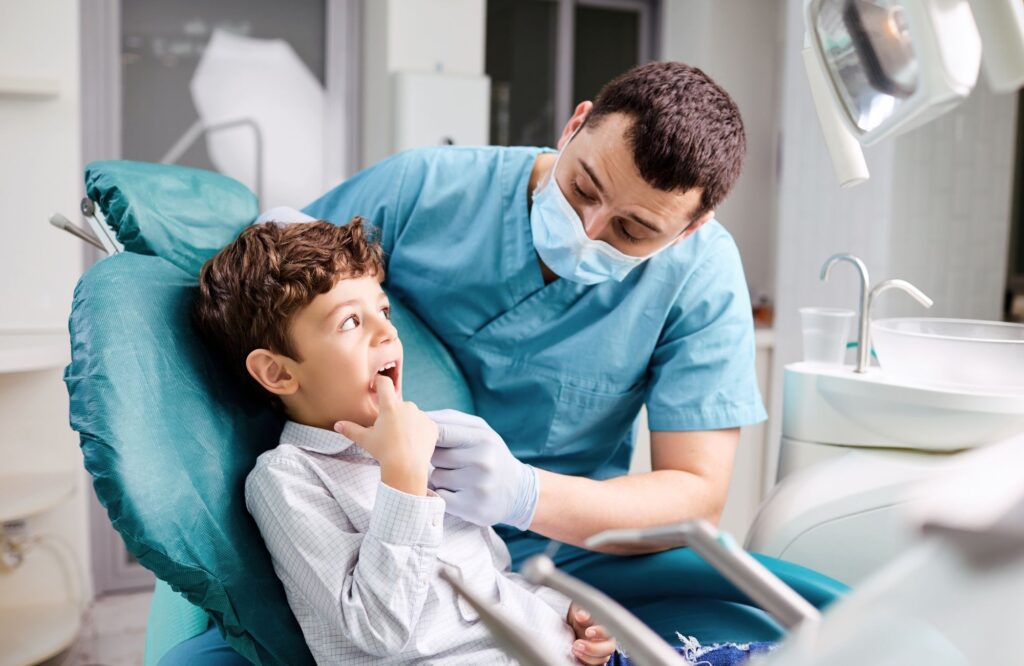
As a dentist, your Dentistry Professional Corporation (DPC) can buy and hold your life insurance. Structuring life insurance within your corporation and using an immediate financing arrangement (IFA) can reduce your family’s tax burden, protect your practice, and help you grow multiple asset streams.
“It’s a great feeling knowing my family will be OK financially when I pass away.” -Andy L., Ontario

Build additional wealth without annual taxation on qualifying insurance policy growth.
Access policy values to help finance real estate and other investments.
Create corporate tax advantages that help preserve more family wealth.
For Ontario dentists, life insurance can do much more than protect their families if they die unexpectedly.
Permanent life insurance owned by a Dentistry Professional Corporation can allow surplus corporate earnings to accumulate on a tax-advantaged basis while creating a potentially much larger tax-free death benefit.
Depending on the policy and financing arrangement, dentists may also be able to borrow against the policy’s cash value to invest in real estate, stocks or other businesses.
At death, corporate-owned insurance can create significant Capital Dividend Account (CDA) room, allowing qualifying amounts to be distributed to shareholders tax-free.
Dentists can use life insurance to protect their families, pay outstanding practice debts, fund business succession and provide liquidity for future estate taxes.
For incorporated dentists, permanent life insurance can also provide an opportunity to reposition some corporate investments into a tax-advantaged policy rather than paying tax annually on certain investment earnings.
Through an Immediate Financing Arrangement (IFA), the policy may be used as collateral to borrow funds for additional investments while maintaining the insurance coverage. This allows dentists to explore building wealth in more than one place while creating a larger tax-free inheritance for their families.
Provides affordable coverage for a specific period and can protect your family against practice loans, mortgages, lost income and other financial obligations.
Provides permanent coverage and cash values, allowing dentists to create long-term estate liquidity and potentially accumulate tax-advantaged wealth.
Combines lifetime protection, guaranteed cash values and potential policyholder dividends that may increase cash values and the death benefit over time.
Provides permanent coverage with flexible deposits and investment options, allowing dentists greater control over how qualifying policy values accumulate.
At SWPP we specialize in helping business owners, real estate investors, and families with complex estates to preserve their wealth.
| Type of insurance | Coverage period | Cost structure | Common use for dentists |
|---|---|---|---|
| Term life insurance | Fixed period | Usually lower initially | Replacing income or covering practice debt |
| Whole life insurance | Lifetime | Usually higher and more predictable | Creating estate liquidity or leaving a legacy, with potential dividends through participating policies |
| Universal life insurance | Lifetime | Flexible but more complex | Combining permanent coverage with investment flexibility |
Policy costs, guarantees, cash values, and tax consequences depend on the specific policy and how the corporation structures and uses it. An Ontario business owner should obtain advice based on the corporation’s needs and financial circumstances.
Life insurance is particularly important when you have a family depending on your income, significant practice debt or business obligations that would need to be addressed if you died unexpectedly.
For dentists with a DPC, permanent insurance should also be evaluated once the corporation begins accumulating surplus earnings. It may allow you to build tax-advantaged wealth, access capital for additional investments and create substantial tax-free liquidity for your family when you die.
As a dentist, you spend years completing your education, establishing your practice and paying down substantial debt before you can begin building significant personal wealth.
Once your professional corporation starts accumulating surplus earnings, you have an opportunity to use permanent life insurance as another financial asset rather than simply treating insurance as an expense.
With the right policy and financing structure, you may be able to deposit corporate funds into life insurance, borrow against the policy, and invest that capital. You can invest the capital in real estate, stocks or other income-producing opportunities. And you can do this while the insurance continues building value.
The real advantage is that you have the potential to build wealth through your investments while also creating a much larger tax-free death benefit.
At the same time you can create CDA room that helps your family receive more of the wealth you have built.
You’ve worked hard and probably want to leave more to your family and less to the government. That’s where the right strategy can help.
EXAMPLE
One of my clients who is a dentist in his early 50s had accumulated significant practice debt and wanted to diversify his wealth beyond dentistry while protecting his family.
We evaluated using surplus earnings from his Dentistry Professional Corporation to fund permanent life insurance, building tax-advantaged cash values and a future tax-free death benefit.
As the policy develops sufficient collateral value, an IFA could allow him to borrow against it to invest in income-producing real estate through an appropriately structured arrangement.
This strategy is designed to help him add additional investments to his portfolio while creating insurance proceeds that could offset estate taxes and provide CDA room for tax-free distributions to his family.
Ultimately it will allow him to leave more to his family.
Life insurance can provide funds to repay practice debts, support business succession, compensate surviving partners or protect your family against the financial consequences of your death. Corporate-owned insurance can also create liquidity to help preserve the value of your practice and other investments.
The amount depends on your income, outstanding practice loans, family responsibilities, corporate investments and future estate tax exposure. We evaluate what your family would need immediately and how much tax-free liquidity may be required to preserve your wealth in the future.
For many incorporated dentists, corporate-owned permanent insurance can provide valuable tax and estate-planning advantages, including funding premiums with corporate after-tax dollars and creating CDA room at death. However, personally owned insurance may be preferable for certain family protection needs, so the ownership structure should be evaluated carefully.
The cost depends on your age, health, coverage amount and type of insurance. With permanent insurance, the more important comparison is often how much you deposit, the cash value created, the tax advantages available and the eventual benefit your family receives.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.
There is no single best policy because the right choice depends on your corporation’s assets, cash flow, investment objectives and estate-planning needs. Participating Whole Life and Universal Life can be particularly worth evaluating when tax-advantaged accumulation, permanent protection and financing flexibility are important.
You may miss opportunities to fund insurance with corporate after-tax dollars, accumulate tax-advantaged policy values and create CDA room that can help distribute corporate wealth tax-free at death. However, corporate ownership also has limitations and risks, so it is not automatically the best choice for every dentist.
Yes. Incorporated and non-incorporated dentists may qualify for an Immediate Financing Arrangement using an eligible permanent life insurance policy as collateral, potentially allowing borrowed funds to be invested in real estate, businesses or other income-producing assets. The arrangement depends on lender approval, policy values, the borrowing structure and applicable tax and professional corporation rules.
Often, yes, because they protect against different financial risks. Disability insurance can replace income if illness or injury prevents you from practising dentistry, while life insurance provides funds to protect your family, repay debts and address estate obligations when you die.
Do you need life insurance? Get started with a zero-obligation life insurance and estate planning consultation today.
Do you need life insurance? Get started with a zero-obligation life insurance and estate planning consultation today.
SWPP helps Ontario dentists and incorporated professionals use life insurance as part of their overall wealth and estate plans. We evaluate corporate-owned insurance, tax-advantaged accumulation, financing opportunities, practice succession and CDA planning to help protect families, preserve investments and transfer more after-tax wealth to the next generation.
At SWPP, we are licensed and recognized advisors. Our goal is to protect your family’s money and assets. We help families, business owners, and real estate investors do comprehensive estate planning in Ontario.
We’re focused on making sure you leave the most for your loved ones instead of giving your hard-earned assets to CRA.
🏡 Ontario Real Estate Investor? Take the Estate Planning Clarity Quiz 💡