GET YOUR LIVING ESTATE PLAN

Insurance for Estate Planning in Ontario

Leave More to Your Family and Less to the Government

Let’s be honest: the CRA wants its cut after someone dies. That’s why proper estate planning is so important. SWPP’s Living Estate Plan ensures your assets are structured in the most tax-efficient way, and includes a full review of all key strategies, including life insurance for estate planning. 

“It’s a great feeling knowing my family will be OK financially when I pass away.” ​-Andy L., Ontario

Estate Tax Protection

Create tax-free liquidity to preserve assets your family would otherwise sell.

Larger Inheritance

Turn existing investment dollars into a potentially greater tax-free family legacy.

Tax-Sheltered Growth

Build qualifying policy values without paying annual tax on internal growth.

What is insurance for estate planning?

Life insurance for estate planning is a strategy that allows you to take a portion of your existing assets and potentially turn it into a much larger tax-free benefit for your family when you die.


Properly structured permanent insurance can also allow qualifying policy values to accumulate on a tax-advantaged basis while providing funds to pay future estate taxes. Rather than simply protecting against an unexpected death, the insurance becomes another financial asset designed to increase the wealth you leave behind.


At SWPP, we evaluate whether life insurance, together with other estate-planning strategies, can help your family receive substantially more of what you have accumulated.

How can you use insurance for estate planning in Ontario?

Sometimes, after reviewing every available estate-planning strategy, you discover that certain future taxes simply cannot be eliminated.


Properly structured life insurance can use a relatively small portion of your existing assets to create a much larger tax-free benefit when you die, providing additional money to pay those taxes rather than forcing your family to use the assets you intended to leave them.


This can allow your children to inherit substantially more of your original estate, potentially approaching what they would have received if those taxes did not exist. Depending on the policy design and future performance, the insurance may even create enough additional wealth to leave your family more than they would have received without the strategy.

Types of Insurance for Estate Planning

Participating Whole Life Insurance

Provides permanent coverage, guaranteed cash values and potential policyholder dividends that can increase policy values and the tax-free death benefit, helping create additional wealth for your family.

Universal Life Insurance

Combines lifetime protection with flexible deposits and investment choices, allowing qualifying policy values to accumulate tax-advantaged while creating liquidity for future estate obligations.

Joint Last-to-Die Life Insurance

Pays the death benefit after the second insured person dies, making it particularly valuable for couples whose largest estate taxes are expected after the second death.

Term Life Insurance

Provides protection for a specified period and can be useful for temporary debts, business obligations or financial responsibilities that may disappear before death.

Immediate Financing Agreement (IFA)

An Immediate Financing Arrangement uses an eligible permanent life insurance policy as collateral for borrowing, potentially allowing you to continue investing borrowed capital while building insurance values and a future tax-free death benefit.

Get an Ontario Life Insurance Quote

At SWPP we specialize in helping business owners, real estate investors, and families with complex estates to preserve their wealth.

Comparing Life Insurance Options for Estate Planning

Insurance Option Coverage Period Premiums Common Estate-Planning Use
Participating whole life Lifetime Typically fixed and higher Creating predictable estate liquidity and preserving wealth
Universal life Lifetime Flexible but requires ongoing management Supporting complex estates that need greater investment flexibility
Joint last-to-die Pays after the second insured person dies Often lower than two separate permanent policies Covering taxes expected after the second spouse’s death
Term life Set period Initially lower Covering temporary debts, loans or business obligations

Policy costs, guarantees, cash values, and tax consequences depend on the specific policy and how the corporation structures and uses it. An Ontario business owner should obtain advice based on the corporation’s needs and financial circumstances.

When do you need life insurance for estate planning?

Life insurance becomes particularly valuable when your estate contains significant RRSPs or RRIFs, investment properties, non-registered investments, corporations or other assets that could create substantial taxes when you die.


If you have accumulated more wealth than you expect to spend during your lifetime, permanent insurance may also allow you to reposition some of that money into a tax-advantaged asset that creates a larger inheritance for your family.

Expert Insights

Most people look at life insurance as an expense that takes money away from their investments, but I look at what happens to their entire estate when they die. 


If you have accumulated $5 million or substantially more, you may already have enough assets to support your lifestyle without spending everything you own. 


By redirecting a portion of those assets into properly structured permanent life insurance, you may be able to reduce annual taxation on investment growth while creating a much larger tax-free death benefit for your family. 


If the insurance doesn’t improve your family’s projected after-tax inheritance compared with keeping the money invested, then we need to reconsider the policy design, or whether life insurance is the right strategy for you at all.

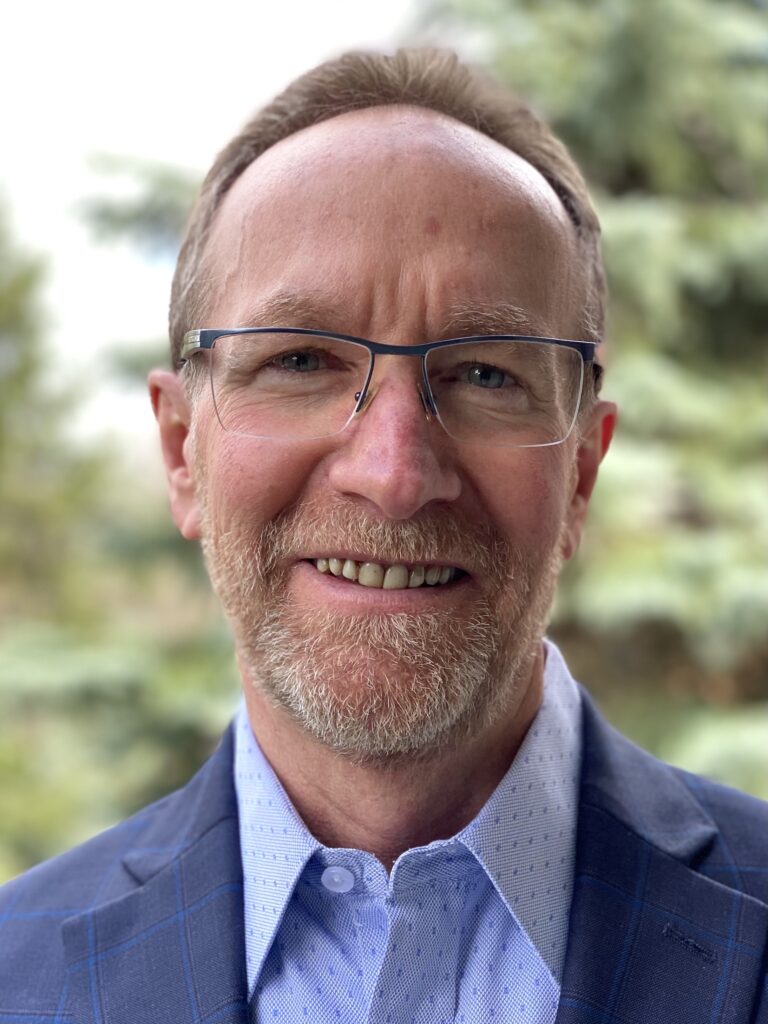
Ron Cooke
SWPP, President and Founder

Client Case Study

How the Living Estate Plan Will Help Provide $1.8M to Cover Taxes on Death

EXAMPLE

Sara, 66, and Tim, 68, had a $1.5 million home, $1.9 million in RRSPs, approximately $245,000 in TFSAs, and $9 million in non-registered investments, with a projected estate tax liability of $1.8 million. 


Through our Living Estate Plan process and discussions with three accountants, we identified a trust and joint last-to-die permanent life insurance as valuable strategies. 


Sara and Tim’s plan involved transferring non-registered assets into a trust and using additional insurance deposits to build tax-advantaged policy values. 


The insurance was designed to return their deposits plus growth and provide approximately $1.8 million in additional tax-free death benefits, potentially replacing the money their children would otherwise lose to estate taxes.

A Great Feeling

It’s a great feeling knowing my family will be OK financially when I pass away.
Andy L
Business Owner and Real Estate Investor, Ontario

Planning & Guidance

We retired several years ago and we're now seeing all the benefits from Ron’s planning and guidance. Knowing our kids will get our assets instead of the government getting them is very pleasing.
Bill and Helen F
Retired, Ontario

Saved $1 Million

Ron’s insurance recommendation will save me over $1 million dollars in taxable income. Everyone should do this!
Mike J
Business Owner and Real Estate Investor, Ontario

Common Questions

Permanent life insurance is often worth considering because estate taxes and other obligations may arise regardless of when you die. Participating Whole Life, Universal Life and Joint Last-to-Die insurance can each provide different advantages depending on your assets, financial objectives and estate structure.

The cost depends on your age, health, coverage amount and how the policy is designed. With permanent insurance, we also evaluate how much of your deposits accumulate as cash value, the potential tax advantages and how much additional wealth your family may ultimately receive.

It can be extremely valuable when the additional tax-free death benefit, tax-advantaged growth and estate liquidity provide a better outcome for your family than leaving the same money invested elsewhere. The important comparison is not simply what the insurance costs, but how much more your family may receive after taxes.

Life insurance can provide tax-free money to pay estate taxes, preserve valuable assets, equalize inheritances and replace wealth lost to taxes. Certain permanent policies can also accumulate tax-advantaged cash values during your lifetime.

Naming an eligible beneficiary directly can allow insurance proceeds to pass outside the estate, potentially avoiding Ontario Estate Administration Tax on those proceeds and providing faster access to funds. Naming the estate may be appropriate when proceeds must be controlled or distributed through your will, but the right designation depends on your overall estate plan.

An Immediate Financing Arrangement allows an eligible permanent life insurance policy to be used as collateral for borrowing, potentially giving you access to capital for other investments while maintaining the insurance. It is not necessary for everyone and should only be considered when the borrowing costs, risks, tax treatment and investment objectives make sense.

The best approach depends on your assets, family circumstances, tax liabilities and how you want your inheritance managed. At SWPP, we compare seven estate-planning strategies, including trusts, corporations, estate freezes and life insurance, to determine which combination can preserve the most wealth for your family.
Key Points & Next Steps

  • If you do not have any key points, remind the senior/writer to create the key points. 
  • Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.
  • Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.
  • Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.

Schedule a Life Insurance Clarity Call

Do you need life insurance? Get started with a zero-obligation life insurance and estate planning consultation today.

Schedule a Life Insurance Clarity Call

Do you need life insurance? Get started with a zero-obligation life insurance and estate planning consultation today.

Related Services

Estate Planning

Discover how SWPP can help you with your Ontario estate plan.

Living Estate Plan

Get a living estate plan that preserves and grows wealth.

Business Life Insurance

Protect your business.

Life Insurance Guides

Types of Permanent Life

Discover the four main types of permanent life insurance.

Taxation of Life Insurance

Find out how taxation on life insurance works in Canada.

Immediate Financing Arrangements

Find out how IFAs work.

About SWPP

We care about you and your family.

SWPP helps Ontario families, business owners, and real estate investors determine whether life insurance can improve their overall estate plan. Through our Living Estate Plan process, we compare insurance with other planning options and evaluate the deposits, cash values, tax advantages, estate liquidity, and ultimately how much more wealth can reach your family.

Ron Cooke
Ron Cooke, President & Estate Planning Expert
John Cooke, Broker & Partner
Kandace Newell, Broker & Partner
Pamela Sedgeworth, Administrative Assistant

SWPP's Mission

At SWPP, we are licensed and recognized advisors. Our goal is to protect your family’s money and assets. We help families, business owners, and real estate investors do comprehensive estate planning in Ontario.  

We’re focused on making sure you leave the most for your loved ones instead of giving your hard-earned assets to CRA.

How Can SWPP Help You?

🏡 Ontario Real Estate Investor? Take the Estate Planning Clarity Quiz 💡